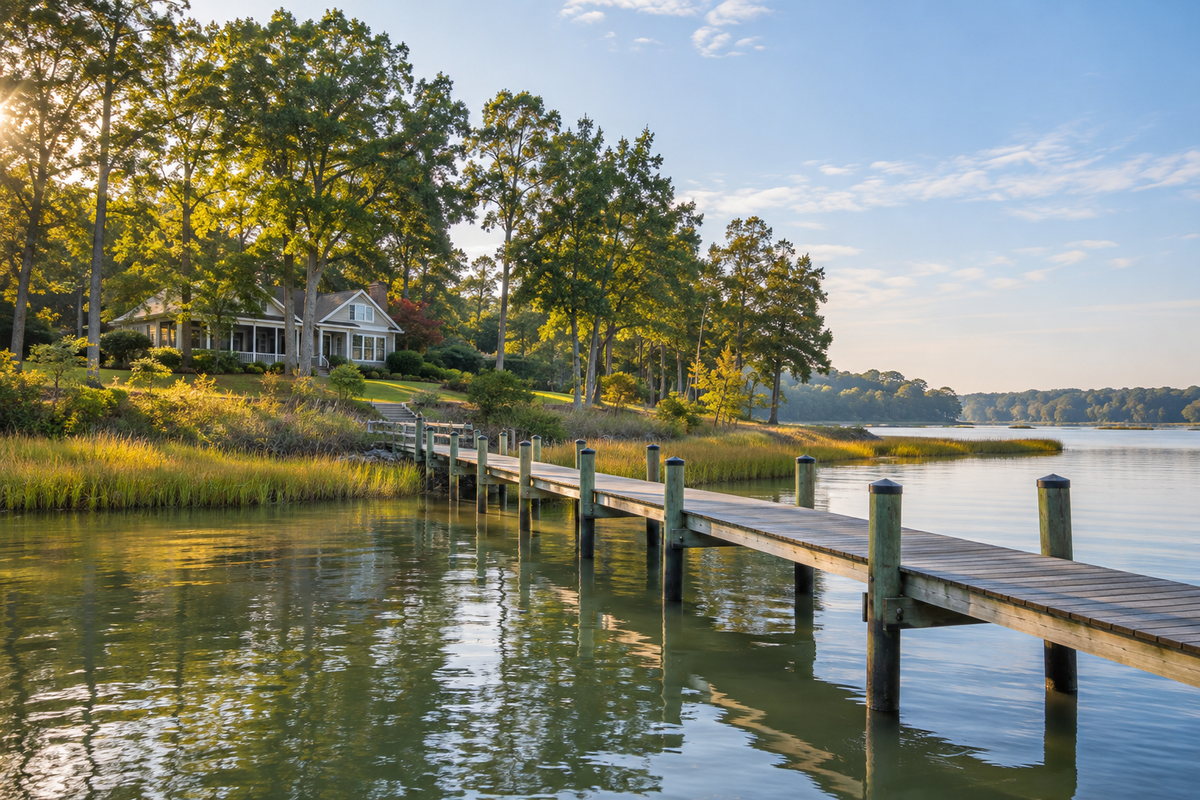
A waterfront home in St. Mary's County comes with more to check than an inland house: the pier and its permits, the depth at low tide, the Critical Area Buffer, the shoreline, the septic system and the flood zone. The county has more than 500 miles of shoreline, according to its county fact sheet, along the Potomac, the Patuxent, the Chesapeake and dozens of creeks, so the details change a lot from one property to the next.
This guide walks through what I check before anyone writes an offer on the water, the state's pier rules, the costs that come with waterfront, and the questions to ask the seller. Waterfront here can be everything you hope it is. It just has more moving parts.
On this page
- Types of waterfront
- The pier and pier rules
- Water depth
- The Critical Area
- The shoreline
- Septic and well
- Flood zones and insurance
- Your inspection team
- Questions to ask the seller
- The true cost of ownership
What Kinds of Waterfront Are There in St. Mary's?
- Open water: big views and breezes on the Potomac, the Patuxent or the bay, with more exposure to wind, waves and storms.
- Creek and cove: calmer water and often better protection for a boat, sometimes with shallower depths.
- Water view vs. water access: a view doesn't always come with a place to launch or tie up a boat.
- Community water access: some neighborhoods share a pier, ramp or beach. Read the rules and fees before you count on it.
Decide which one you actually want before we tour. A wide-open Potomac view and a protected creek slip are different purchases with different upkeep.
What Should I Know About the Pier?
Start with condition and paperwork. Look at the pilings, decking and any boat lift, and hire someone who inspects marine structures, not just a home inspector. Then ask the seller for the permits behind the pier, lift and any bulkhead.
Three levels of government review pier work in Maryland's tidal waters, according to the Maryland Department of the Environment. The county handles building permits and setbacks, while MDE's Tidal Wetlands Division and the U.S. Army Corps of Engineers review the state and federal side through one joint application. In St. Mary's, the county side runs through the Department of Land Use and Growth Management.
Maryland Residential Pier Limits
General MDE guidelines; your site may differ
- Extends no more than 150 feet from land, or one-quarter of the waterway's width, whichever is less
- Main walkway up to 6 feet wide over open water (3 feet over vegetated wetlands)
- Platforms up to 200 square feet
- Up to 4 boat slips plus 2 for jet skis or smaller craft
- Can't cross your property lines, and county setbacks apply
If you plan to add or lengthen a pier, don't assume it's possible on a narrow creek or a tight lot. MDE offers an expedited license for residential fixed piers that meet its checklist, but a pier inside the county's side setback needs a variance. Ask before you build the plan into your offer.
MDE describes these as general limits. What actually gets approved depends on the site and the waterway, so a pier at the maximum size isn't guaranteed on any property.
How Deep Is the Water at the End of the Pier?
A pier is only as good as the water at the end of it. Visit at low tide, ask the seller what boat they kept there, and if you have a specific boat in mind, check the depth before you commit. Some creeks are fine for kayaks and too shallow for anything with a deep draft.
What Is the Critical Area, and How Does It Affect My Plans?
All land within 1,000 feet of tidal water or tidal wetlands is in Maryland's Critical Area, and the first 100 feet from the water is a protected Buffer, according to the Maryland DNR Critical Area FAQ. The Buffer can be wider on steep slopes or near wetlands.
Those are the general statewide rules. Whether a specific lot is in the Critical Area, how wide its Buffer is, and what you can build or clear there depend on the county's mapped boundaries and a review of that parcel. Confirm with St. Mary's County Land Use and Growth Management before you count on a plan.
- Trees in the Buffer can only come down if they're dead, dying, diseased or hazardous, so a view-clearing plan may not fly.
- Construction, clearing and grading are generally prohibited in the Buffer.
- Plans for a new deck, addition, shed or pool should be checked with the county before you count on them.
My Critical Area and 100-foot Buffer guide covers lot coverage limits and variances.
What Should I Look For on the Shoreline?
Look at the bank, the marsh and any existing bulkhead or stone. Erosion is a real long-term cost, and Maryland's Living Shoreline Protection Act makes natural, living shorelines the default, with bulkheads and revetments allowed only in certain cases. Read my guide to shorelines and erosion before you buy.
Does a Waterfront Home Need a Special Septic System?
Many waterfront homes here run on septic and a private well. If a septic system in the Critical Area ever needs replacing, Maryland requires a nitrogen-removing BAT system under COMAR 26.04.02.07, and it costs more than a standard one. Get a septic inspection and a well water test during your inspection period, and see septic replacement and BAT in St. Mary's for grants and upkeep.
How Do Flood Zones and Flood Insurance Work on the Water?
Check the FEMA flood zone for any waterfront home, then get a flood insurance quote early. You can look up an address on the FEMA Flood Map Service Center or on the county's GIS map, and the St. Mary's County floodplain office at 301-475-4200, ext. 1523, can help with residential questions. If the home is in a high-risk zone and you're using a federally backed mortgage, your lender will require flood insurance.
Two timing details matter. National Flood Insurance Program policies cover up to $250,000 for the structure and $100,000 for contents, and new policies have a 30-day waiting period, according to FEMA. There are exceptions: there's no waiting period when the policy is bought in connection with making, increasing, extending or renewing a loan, and a 1-day wait applies within 13 months after a flood map revision, per FEMA's rules as summarized by Berkeley County, S.C.. Confirm your policy's effective date with your insurance agent before settlement.
Ask the seller for an elevation certificate. If there isn't one, it has to be completed by a licensed engineer or surveyor, per the county. On some waterfront homes, insurance moves your monthly cost more than the interest rate does.
Do I Need a New Survey?
Make sure the pier, the shoreline, the house and your property lines all match on a current survey. Erosion can change where the water's edge actually is, and a pier can't cross your property line under MDE's rules, so you want to know exactly what you're buying.
Who Should Be on My Inspection Team?
Your Waterfront Inspection Team
Who checks what
The house
- Home inspector
- Septic inspector
- Well water test
The water side
- Marine contractor for pier, lift and bulkhead
- Surveyor, if lines are unclear
- Flood insurance quote and elevation certificate
Book the marine contractor as soon as you're under contract, since your inspection window doesn't wait.
What Does a Waterfront Purchase Look Like Step by Step?
Example scenario: This is made up to show the order of checks, not a real sale. A buyer finds a creekfront rambler near Hollywood with an older pier and a boat lift.
Before writing an offer, we visit at low tide and look up the flood zone. The offer includes time for a home inspection, a septic inspection, a well test and a marine contractor's look at the pier and lift. The seller provides an old pier permit but no elevation certificate, so the buyer orders one and gets a flood quote in the first week.
The marine contractor finds several pilings near the end of life. The buyer now knows the real cost of the pier before settlement, not after the first storm, and can decide what to ask for with real numbers in hand.
What Mistakes Do Waterfront Buyers Make?
- Touring only at high tide. The water you see at noon may not be there at 6 a.m.
- Assuming the pier is permitted. Ask for the paperwork, and check that the pier stays inside the property lines.
- Planning to clear the view. The 100-foot Buffer limits which trees can come down.
- Getting the flood quote last. Insurance can change your monthly budget more than your rate does.
- Skipping the marine inspection. A home inspector isn't trained to judge pilings or a bulkhead.
Check the water side as carefully as the house. That's where the surprises on a waterfront purchase usually come from.
What Affects Waterfront Value?
Waterfront homes vary a lot in value based on depth, exposure, views, shoreline condition and what can be built. Two homes on the same creek can be worth very different amounts. When I help you price an offer, I look at all of it, not just square footage. Thinking about selling a waterfront home instead? Start with a free valuation.
Where Is the Waterfront in St. Mary's County?
Waterfront shows up all over the county, from Piney Point, St. Inigoes and Ridge to the creeks around Leonardtown and Hollywood. Tell me what kind of water you want, whether that's deep water for a boat, a quiet creek or a big view, and I'll narrow it down. Compare areas in the best areas to live in St. Mary's County.
What Should I Ask the Seller?
- How deep is the water at the end of the pier at low tide, and what boat did you keep here?
- When were the pier, lift and bulkhead built or repaired, and were they permitted?
- Has the shoreline changed while you've owned the home? Any erosion work?
- When was the septic last pumped and inspected? Any well water tests?
- Has the home ever flooded? Do you have an elevation certificate?
- What do you pay for homeowners and flood insurance?
What Does Waterfront Really Cost to Own?
Waterfront homes come with costs that inland homes don't: flood insurance in high-risk zones, pier and lift maintenance, shoreline work over time, and sometimes a more expensive septic system. None of that is a reason not to buy. It's a reason to budget for it up front, so the water stays a joy instead of a surprise.
Ready to look? Tell me what you're after, and I'll check the pier, the permits and the flood zone before we ever write an offer.
Frequently Asked Questions
Work in tidal waters generally needs state and federal approval through the joint Maryland Department of the Environment and Army Corps of Engineers tidal wetlands application, plus county review. Ask before you assume a new or longer pier is possible. See waterfront homes in Piney Point, St. Inigoes and Ridge.
Not freely. Land within 1,000 feet of tidal water is in the Critical Area, and trees in the 100-foot Buffer can only come down if they're dead, dying, diseased, or hazardous. More in my St. Mary's buyer's guide. The rules are explained in the Critical Area and 100-foot Buffer guide.
The pier and any bulkhead, shoreline erosion, the septic system (a Critical Area replacement has to be a BAT system), and the flood zone, with an insurance quote early. My waterfront checklist walks through it. If the septic needs replacing, see septic replacement and BAT in St. Mary's. For a closer look at parcel-level flood questions around Piney Point, St. Inigoes and Ridge, see my Lower Peninsula flood-zone guide.
Generally no more than 150 feet from land or one-quarter of the waterway's width, whichever is less, according to the Maryland Department of the Environment. County setbacks also apply. See my buying page to start a waterfront search.
MDE's general guideline for a residential pier is up to four boat slips plus two for jet skis or smaller craft, with platforms up to 200 square feet. Your exact approval depends on the site. Compare waterfront areas in the best areas to live in St. Mary's County.
Usually 30 days for a new National Flood Insurance Program policy, according to FEMA, but there's no wait when the policy is bought with a new or refinanced loan, and a 1-day wait after a flood map revision. Confirm the effective date with your agent before settlement. My affordability guide shows how insurance fits your budget.
Sources: St. Mary's County fact sheet · MDE: Guide to building and changing piers · MDE/USACE tidal wetlands application booklet · Maryland DNR Critical Area FAQ · COMAR 26.04.02.07 (BAT septic) · Maryland's Living Shoreline Protection Act · St. Mary's County floodplain management · FEMA: flood insurance coverage and waiting period · FEMA Flood Map Service Center · Berkeley County, S.C.: NFIP waiting period exceptions. Checked October 2026; rules and rates can change, so confirm anything that affects your decision.
This article is general real estate information, not legal, lending, tax, or insurance advice. Talk with the right licensed professional about your specific property.
Thinking About Buying in St. Mary's?
Tell Nicole what you're looking for and she'll send matching homes, with the local details checked.
Tell Me What You're Looking For Schedule a Consultation